- Who files
- Holders with New Mexico property, 25 items or fewer on paper
- Due
- Before November 1 (life insurers before May 1)
- Filed with
- Taxation and Revenue Department, Unclaimed Property Office
- Form revision
- Rev. 02/27/2024
- Pages
- 1, plus the owner lists
At a glance
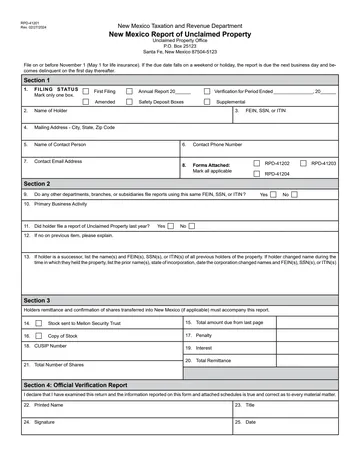
RPD-41201, New Mexico Report of Unclaimed Property, is the summary page of a paper unclaimed property report to the New Mexico Taxation and Revenue Department (TRD), Unclaimed Property Office. It sits on top of the owner lists (RPD-41202, RPD-41203, RPD-41204), totals them and carries the signed verification. It is page 9 of the RPD-41200 Holder's Filing Kit (Rev. 02/27/2024, current as of November 2026), with its instructions on pages 10 and 11.
- Who files it. “All holders, whether located in New Mexico or in other states, must report to the State of New Mexico any unclaimed property they hold that is owed to New Mexico residents.” Holders domiciled in New Mexico also report property whose owner's name and address are unknown.
- When. The form says “File on or before November 1 (May 1 for life insurance)”, and “If the due date falls on a weekend or holiday, the report is due the next business day”. The statute says the report “must be filed before November 1 of each year and cover the twelve months next preceding July 1 of that year” (NMSA 7-8A-7(D)), with life insurers before May 1. The statute governs; file by October 31 and you meet both.
- How. On paper only for small reports: “A holder with fewer than 25 properties to report may file using the form RPD-41201 and RPD-41202.” Larger reports go through the Online Holder Reporting Module as a NAUPA file (see paper or online).
- Where. Taxation and Revenue Department, Attn: Unclaimed Property Office, P.O. Box 25123, Santa Fe, NM 87504-5123; 505-827-0668; Unclaimed.Property@tax.nm.gov.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
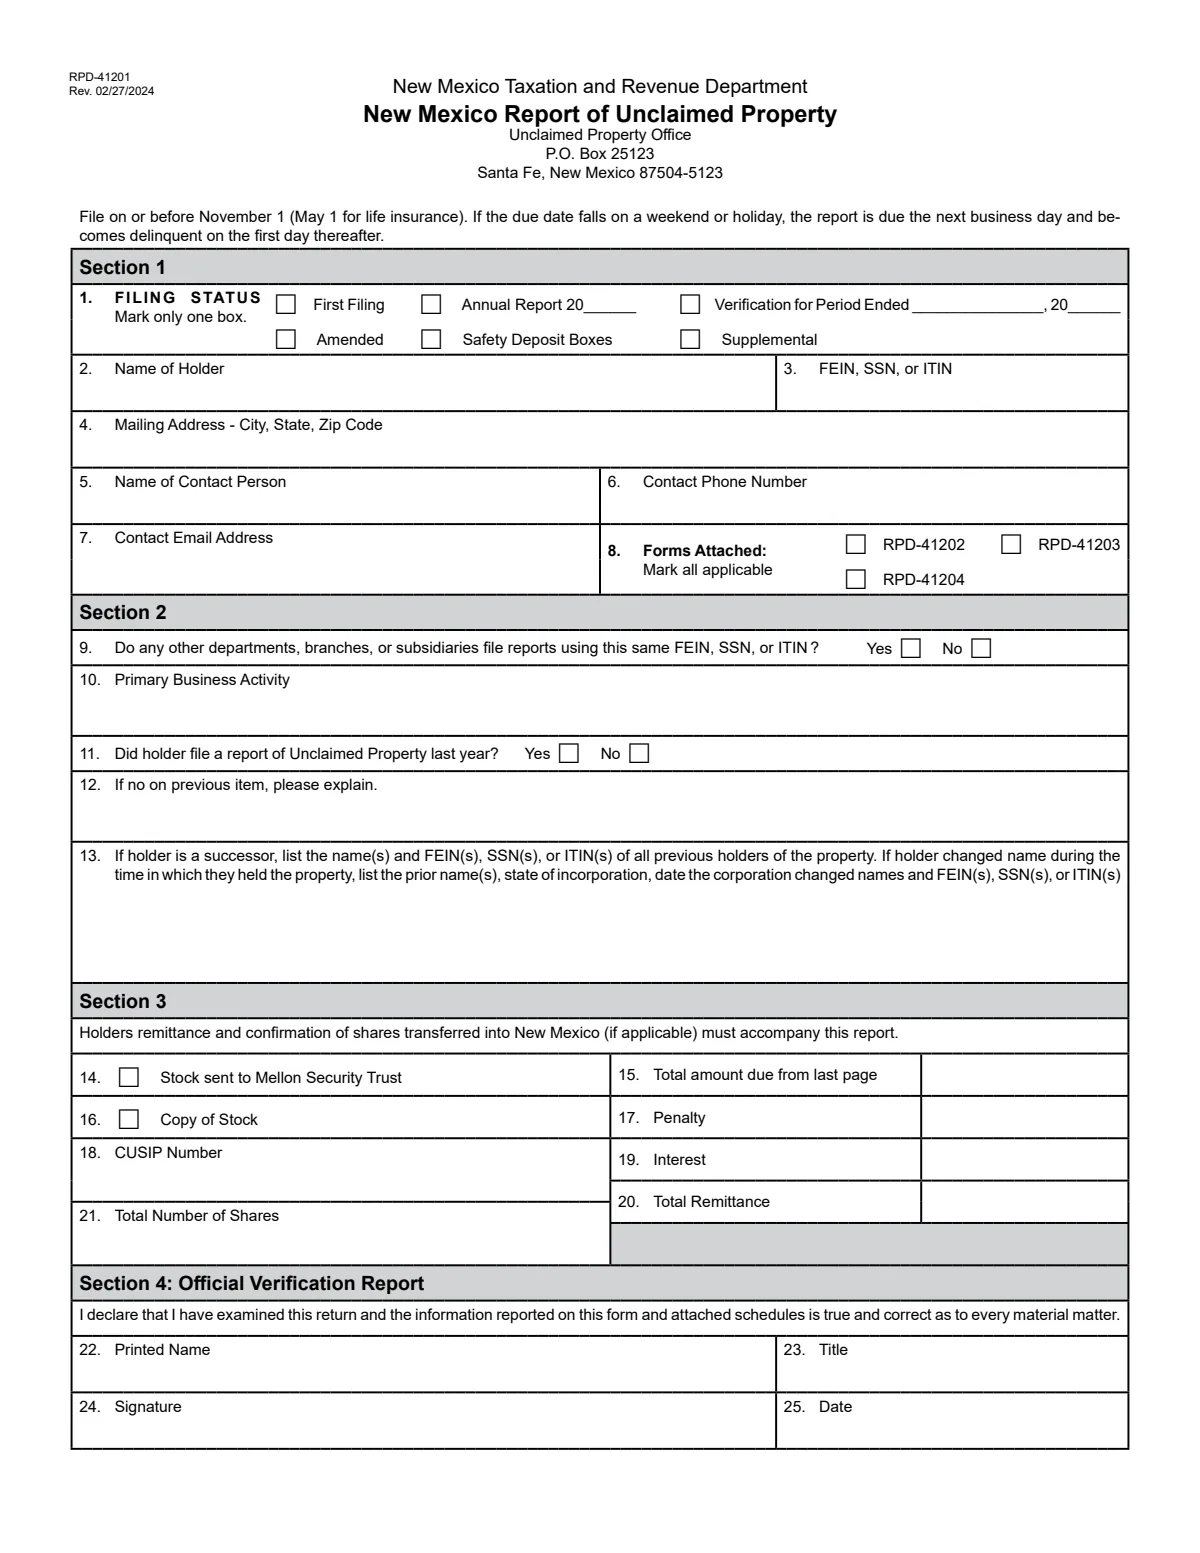
Section 1: holder and contact (lines 1 to 8)
Section 1 says what kind of report this is and who sent it. The instructions for most lines are one sentence; the notes below add what the rest of the kit says.
| Line | Label | What goes there |
|---|---|---|
| 1 | FILING STATUS: First Filing; Annual Report 20__; Verification for Period Ended __, 20__; Amended; Safety Deposit Boxes; Supplemental | “Mark only one box to indicate filing status.” With Annual Report, write the report year; with Verification for Period Ended, the month and year. The kit's FAQ gives the date to use there: “Enter June 30 of the current fiscal year for corporations and December 31 for life insurance companies.” Supplemental is for property found after you filed: the kit says not to combine it with accounts already reported, to “Prepare a new report and indicate in a cover letter that it is a supplemental filing.” Safety Deposit Boxes goes with an RPD-41204 contents list. |
| 2 | Name of Holder | “Enter the name of the holder.” Use the same name as on the owner lists attached; one RPD-41201 summarizes one report. |
| 3 | FEIN, SSN, or ITIN | “Enter the FEIN, SSN, or ITIN of the holder.” A business uses its FEIN; an SSN or ITIN is for an individual holder such as a sole proprietor. |
| 4 | Mailing Address - City, State, Zip Code | “Enter the complete mailing address of the holder.” The kit adds: “It is the holders responsibility to keep UPO advised of a current address and any changes in the contact person or unit responsible for filing reports.” |
| 5 | Name of Contact Person | The person who prepared the report or can answer for it. The kit says the report “requires that you provide your Federal Tax ID, current address, contact person, phone number and E-mail address.” |
| 6 | Contact Phone Number | A direct number for the contact person. |
| 7 | Contact Email Address | The contact person's email address. |
| 8 | Forms Attached: RPD-41202, RPD-41203, RPD-41204 (mark all applicable) | Mark every list attached. RPD-41202 lists owners of cash items (checks, wages, credits, refunds); RPD-41203 lists owners of stocks and other securities; RPD-41204 lists safe deposit box and safekeeping contents. RPD-41201 only summarizes them: the instructions say the form “is used to summarize the report information from” those three lists. On RPD-41202, “Please total all amounts due to each owner and enter a single grand total for each owner listed on your report.” |
Section 2: about the holder (lines 9 to 13)
Section 2 helps the office match this report to the holder's history: other filers under the same number, last year's report, and any predecessor whose property is on this one.
| Line | Label | What goes there |
|---|---|---|
| 9 | Do any other departments, branches, or subsidiaries file reports using this same FEIN, SSN, or ITIN? Yes / No | “Mark only one box to indicate yes or no to question.” Answer Yes when, for example, a subsidiary or division files its own New Mexico report under the parent's FEIN, so the office does not treat the two reports as duplicates. TRD's holder page puts the duty on the business as a whole: “All business entities are responsible for filing reports on behalf of their branches, divisions or other affiliates.” |
| 10 | Primary Business Activity | “Briefly describe the nature of the type(s) of business in which you are engaging.” A few words is enough: retail, oil and gas production, staffing, software. |
| 11 | Did holder file a report of Unclaimed Property last year? Yes / No | Mark one. A first-time filer marks No here and First Filing on line 1. |
| 12 | If no on previous item, please explain. | “If you indicated no to the previous question provide a brief explanation.” For example: first year with New Mexico owners, nothing to report last year, or a newly formed business. A holder that should have reported in past years and did not may want to read about voluntary disclosure before it writes the explanation. |
| 13 | If holder is a successor ... If holder changed name during the time in which they held the property ... | Two cases. A successor lists “the name(s) and FEIN(s), SSN(s), or ITIN(s) of all previous holders of the property”. A holder that changed its name lists the prior names, the state of incorporation, the date the name changed and the numbers. This is the statute's successor rule: the holder “shall file with the report its former names, if any, and the known names and addresses of all previous holders of the property” (NMSA 7-8A-7(C)). Attach a sheet if the box is too small. |
Section 3: totals, payment and shares (lines 14 to 21)
The form prints the rule for this section: “Holders remittance and confirmation of shares transferred into New Mexico (if applicable) must accompany this report.” The cash lines (15, 17, 19, 20) run down the right side; the securities lines (14, 16, 18, 21) down the left.
| Line | Label | What goes there |
|---|---|---|
| 14 | Stock sent to Mellon Security Trust | “Mark box to indicate that stocks indicated on RPD-41203 have been delivered to” the department's transfer agent. The label carries the agent's name as printed on the 2024 form. TRD's reporting methods page (read November 2026) gives the current delivery steps: “At least two days prior to delivery, email an intent to deliver property to our custodian”, and “All DTC (Depository Trust Company) -eligible shares must be delivered through DTC at the below instructions or via Direct Registration System (DRS).” Use the registration and account details on that page, not the name on the form. |
| 15 | Total amount due from last page | “Enter the total amount due of all pages of RPD-41202, RPD-41203, and RPD-41204 as applicable to this return.” Items under $50 may be totaled: “Individual owner accounts of less than $50 may be reported as aggregate.” The statute allows “an aggregated amount of items valued under fifty dollars ($50.00) each” (NMSA 7-8A-7(B)(3)). |
| 16 | Copy of Stock | “Mark box to indicate that shares have been delivered to the Departments stock custodian.” Physical certificates need the custodian's approval first; the reporting methods page says to “Deliver a photocopy of the certificate with your report and send the original certificate to our custodian.” |
| 17 | Penalty | “Enter the amount of penalty applicable.” Leave it blank on a report filed on time. For a late report, the instructions repeat the statute: a holder that fails to report, pay or deliver on time owes “a civil penalty of one hundred dollars ($100) for each day the report, payment or delivery is withheld, or the duty is not performed, up to a maximum of five thousand dollars ($5,000)” (NMSA 7-8A-24(b)). Willful failure is $250 a day up to $7,500 plus 25 percent of the unreported value; a fraudulent report is $500 a day up to $12,500 plus 25 percent. The administrator “shall waive penalties if the holder acted in good faith and without negligence” (NMSA 7-8A-24(e)). |
| 18 | CUSIP Number | The CUSIP of the securities you deliver: the instructions describe it as a number “which consists of nine” characters, letters and numbers, that identifies the issuer and the type of instrument. List each CUSIP on RPD-41203 if there is more than one issue. |
| 19 | Interest | Only for property reported, paid or delivered late. The statute sets interest “at the annual rate set forth in Section 7-1-67 NMSA 1978” (NMSA 7-8A-24(a)); the instructions explain that the rate follows the IRS rate for individual income tax, changes each quarter and is applied daily: “Tax Due X Daily Interest Rate for the Quarter X Number of Days Late = Interest Due.” TRD posts the rates on its penalty and interest rates page. |
| 20 | Total Remittance | The amount you pay with the report: line 15 plus any penalty and interest. Make the check payable as the reporting methods page says, “Make all checks payable to ‘New Mexico Taxation and Revenue Department, Unclaimed Property Office’ for the total amount listed on the Unclaimed Property Report.” The same page prints a shorter payee too, so match one of TRD's wordings exactly. The kit asks: “Please prepare one check for each report you file.” Online filers can pay by ACH debit in the module instead. |
| 21 | Total Number of Shares | “Enter the total number of shares from RPD-41203.” |
Section 4: Official Verification Report (lines 22 to 25)
| Line | Label | What goes there |
|---|---|---|
| Decl | Section 4: Official Verification Report. I declare that I have examined this return ... | The signer declares: “I declare that I have examined this return and the information reported on this form and attached schedules is true and correct as to every material matter.” This is the verification the statute requires (“The report must be verified”, NMSA 7-8A-7(B)). It is not notarized: the kit's FAQ answers “Do I need to notarize my report? No.” |
| 22 | Printed Name | “Enter the printed name of signer.” |
| 23 | Title | “Enter the title of signer.” The statute does not require a particular officer. |
| 24 | Signature | The signer's signature, after the letters have gone out and the lists are final (see the due diligence affidavit below). |
| 25 | Date | The date signed, in the form's format mm/dd/ccyy (for example 10/28/2026). |
The statute also asks for a due diligence affidavit with every report: the holder “shall file with the report an affidavit stating that the holder has complied with Subsection F of this section” (NMSA 7-8A-7(H)). RPD-41201 has no separate affidavit box; online, the module's “Verification and Affidavit” check box does that job. On paper, the Section 4 declaration covers the report and its attached schedules; a short signed statement that the letters were sent, attached to the report, meets the statute's words. That attachment is our reading of 7-8A-7(H), not a TRD instruction.
Paper or online
The statute draws the line at 25 properties: “A holder of more than twenty-five properties presumed abandoned shall report the properties in an electronic media and in a format determined by the administrator” (NMSA 7-8A-7(E)). TRD's own words: “Effective July 1, 2006, all reports containing more than 25 properties are required to be submitted electronically.” The electronic format is the NAUPA file, uploaded to the Online Holder Reporting Module; the reporting methods page says TRD “will no longer accept electronic media this includes USB and compact disks”. A computer printout can stand in for the paper lists only if it has every field: “Property type codes must appear on the printout.”
NMSA 7-8A-7(E); RPD-41200 filing kit (02/27/2024); TRD reporting methods page (read November 2026).
When you file on paper, the reporting methods page warns: “When reporting on paper form, type or print all information clearly or the form will be returned as incomplete.” Property type codes come from the Unclaimed Property Retention Period and Property Type Codes Schedule printed after RPD-41201 in the kit (see the NAUPA file format page for how the codes work).
Rules that trip holders up
- The letter window. Before filing, the holder must write to each owner of property worth $50 or more whose address its records do not show to be wrong, “not more than one hundred twenty days or less than sixty days before filing the report” (NMSA 7-8A-7(F)). The kit prints only the first half (not more than 120 days); the statute also sets the 60-day floor, and the statute governs. For a report filed October 30, mail between July 2 and August 31. See due diligence letters.
- One check, one report. Separate checks for separate reports, payable exactly as TRD prints it.
- One line per owner. Add up everything owed to an owner and report one total.
- Out-of-state owners. Report property to the state of the owner's last known address; the kit says property sent to New Mexico for another state's owner “will be forwarded to the correct state in the year after it is remitted to New Mexico”. It is still better to file with the right state the first time (which state gets it).
- Extensions. Ask in writing before the due date on RPD-41096, Extension of Time to File (TRD's extension page); TRD's page says to “Submit the form to the Unclaimed Property Office before the due date for filing the report.” An extension does not stop interest: “Authorization of an extension applies only to report filing and penalty.” Pay by the due date to avoid interest.
- Records. Keep the records behind the report “for ten years after the holder files the report” (NMSA 7-8A-21(a)).
How it connects
- The state's rules: New Mexico unclaimed property.
- Nothing to report this year: RPD-41205, Holder's Negative Report and the negative report finder.
- Lines 17 and 19: penalties and interest and the penalty estimator.
- The report itself: unclaimed property reporting and the NAUPA file format.
- The letters before the report: due diligence letters.
Questions holders ask
Can I file RPD-41201 on paper?
Only if the report has 25 properties or fewer. Reports with more than 25 properties must be filed electronically in the NAUPA format through the Online Holder Reporting Module, and TRD no longer accepts USB drives or CDs.
Does the New Mexico report need a notary?
No. The kit's FAQ answers the question directly. Section 4 is a signed declaration that the report and schedules are true and correct.
What date goes in Verification for Period Ended?
June 30 of the current fiscal year for most holders, and December 31 for life insurance companies, according to the kit's FAQ.
Who do I make the check out to?
The New Mexico Taxation and Revenue Department, Unclaimed Property Office (TRD's pages also print shorter versions of the name). Send one check for each report.
When do I mail New Mexico due diligence letters?
Between 120 and 60 days before you file, to owners of property worth $50 or more with an address your records do not show to be wrong (NMSA 7-8A-7(F)).
Does an extension stop interest?
No. TRD says an extension covers report filing and penalty only. Pay by the due date, with a copy of the approved extension, to avoid interest.
Sources
- RPD-41200, Unclaimed Property Report, Holder's Filing Kit, with RPD-41201 (Rev. 02/27/2024) (PDF)
- Reporting methods and requirements, New Mexico Taxation and Revenue Department
- Who must report unclaimed property, TRD
- When to file an extension, TRD
- NM Holder Manual, Online Holder Reporting Module (Revised 02/2022) (PDF)
- NMSA 1978, 7-8A-7 and 7-8A-24, Uniform Unclaimed Property Act (1995), NMOneSource